Government Loan Schemes for Entrepreneurs in India 2026: Compare Eligibility and Costs
08, Oct 2026
20
Government-backed finance can help an Indian entrepreneur purchase equipment, fund working capital or establish an eligible enterprise. However, the phrase “government business loan” covers different arrangements. Some programmes support loans made by financial institutions, some include a credit-linked subsidy and others provide a guarantee to the lender. They are not interchangeable, and none means every applicant receives money automatically.
This guide compares important nationwide options using official information reviewed on 8 October 2026. Choose according to your business activity, stage and eligibility rather than the largest advertised limit. Interest rates, documentation and sanction decisions still depend on the programme and lender. Check the latest application rules before committing to a purchase or assuming a subsidy will be available.
Understand loans, subsidies and guarantees
A loan must be repaid according to the sanction terms. A subsidy is support provided under specific conditions, sometimes linked to a financed project rather than paid freely into your account. A credit guarantee protects an eligible lender against part of its risk; it does not cancel the borrower's repayment obligation or replace the lender's appraisal.
Compare the full borrowing cost: interest, processing charges, applicable guarantee fees, insurance requirements and repayment timing. Ask for the terms in writing. A lower instalment created by a longer tenure can still mean a higher total interest cost. Borrow for a defined business need and test whether repayments remain affordable during a slow sales period.
1. Pradhan Mantri MUDRA Yojana
PMMY supports eligible micro-enterprise activities through participating lending institutions. The categories are Shishu for loans up to ₹50,000, Kishore above ₹50,000 and up to ₹5 lakh, Tarun above ₹5 lakh and up to ₹10 lakh, and Tarun Plus above ₹10 lakh and up to ₹20 lakh. Tarun Plus is specifically for entrepreneurs who have successfully repaid a previous Tarun-category loan.
The ₹20 lakh limit therefore does not mean a first-time applicant can automatically obtain ₹20 lakh. Explain the business purpose, present credible costs and discuss eligibility with a participating lender. The scheme supports collateral-free credit under its framework, but lenders still assess the application. There is no universal interest rate or promise that weak credit or incomplete documents will be ignored.
2. Prime Minister's Employment Generation Programme
PMEGP is a credit-linked subsidy programme for eligible new micro-enterprises. Published limits for projects eligible for margin-money subsidy are ₹50 lakh for manufacturing and ₹20 lakh for business or services. General-category subsidy rates are 15% in urban areas and 25% in rural areas; specified special categories have 25% urban and 35% rural rates.
Own contribution is generally 10% for the general category and 5% for special categories. Eligibility, education requirements for larger projects, the negative list and prior government-subsidy restrictions require careful checking. Apply through the official PMEGP route and prepare a project report. Subsidy is subject to programme conditions and adjustment processes; do not describe it as an immediate cash gift or assume sanction merely because an application was submitted.
3. PM Vishwakarma for eligible artisans
PM Vishwakarma is designed for eligible traditional artisans and craftspeople in specified trades, rather than every type of startup. Its enterprise-development credit component provides up to ₹1 lakh in the first tranche and up to ₹2 lakh in the second, at a concessional beneficiary interest rate of 5%, subject to scheme conditions. The respective repayment tenures are 18 and 30 months.
The two tranches are progressive support, not an automatic ₹3 lakh payment on registration. Skill-training and subsequent eligibility conditions apply. Confirm your trade, household eligibility and earlier credit-scheme history through the official programme. Where needed, use an authorized Common Service Centre for assistance. Keep the distinction between credit, training and toolkit support clear when planning your business expenses.
4. PM SVANidhi for eligible street vendors
PM SVANidhi is targeted working-capital support for eligible street vendors. Under the restructured programme, the progressive loan tranches are ₹15,000, ₹25,000 and ₹50,000. The lending period has been extended to 31 March 2030. It is a vendor-focused programme, not a general loan for any student, online seller or aspiring company founder.
Check vendor identification and local-body requirements through the official application process. Progression depends on the applicable repayment and eligibility conditions. Work out how stock purchases will generate enough cash for repayments, and distinguish scheme incentives from core business revenue. Avoid using outdated articles that still present the earlier first and second tranche amounts as the current structure.
5. CGTMSE-backed lending support
CGTMSE facilitates credit-guarantee support for eligible micro and small enterprises through member lending institutions. Official information states that the eligible credit ceiling under the main framework increased to ₹10 crore from 1 April 2025. This is a scheme ceiling, not a standard loan offer or a promise that a small new business qualifies for that amount.
You approach a participating lender for the credit facility and discuss whether applicable guarantee coverage can support it. CGTMSE does not directly hand a loan to the entrepreneur. Coverage, fees and security arrangements depend on the applicable product and rules. Ask the bank which charges apply to you and how the guarantee is reflected in the proposed sanction terms.
Match the option to the business need
A small shop seeking modest working capital may first discuss PMMY with a lender. An eligible new manufacturing or service project may investigate PMEGP's credit-linked subsidy. A qualifying traditional craft worker should check PM Vishwakarma, while a street vendor should check PM SVANidhi. An eligible MSE considering a bank facility can ask about CGTMSE support.
These are starting points for comparison, not recommendations that you qualify. Avoid applying randomly to several products without understanding eligibility. State-specific schemes may offer additional routes, but their rules are not nationwide. Use the verified requirements for your state and business, and do not combine subsidies unless the relevant rules allow it.
Prepare a stronger application
Organize identity and business documents, applicable registrations, bank statements, supplier quotations and a clear project report. The lender or programme will specify the actual list. Explain what the money buys, how customers will pay and how instalments will be funded. Forecast sales conservatively and include working capital rather than allocating everything to machinery or interior decoration.
Our business-starting guide helps organize the venture before finance. Use the 30-day business validation plan to gather demand evidence. Never pay an unofficial intermediary for “guaranteed approval,” share banking passwords or treat a message from an unknown number as a sanction letter.
Frequently asked questions
Which government loan scheme is best?
The suitable option depends on activity, eligibility, finance needs and repayment capacity. Compare the actual sanction terms instead of choosing solely by the advertised maximum amount.
Can a first-time borrower get Tarun Plus?
Tarun Plus requires successful repayment of a previous Tarun-category loan. First-time borrowers should discuss the category appropriate to their business with a participating lender.
Does a guarantee mean I do not repay?
No. Guarantee support is part of the lender's risk framework. You remain responsible for the loan obligations stated in your agreement.
Are all these schemes interest-free?
No. They have different pricing and support arrangements. Request written details of interest, fees, instalments and applicable subsidy conditions before accepting finance.
Official sources: DFS PMMY, KVIC PMEGP, PM Vishwakarma, PIB PM SVANidhi and CGTMSE. Information reviewed 8 October 2026; confirm current terms before applying.
Tags: Government Loan Schemes, MUDRA, PMEGP, MSME Finance, PM Vishwakarma, PM SVANidhi, Entrepreneurship.
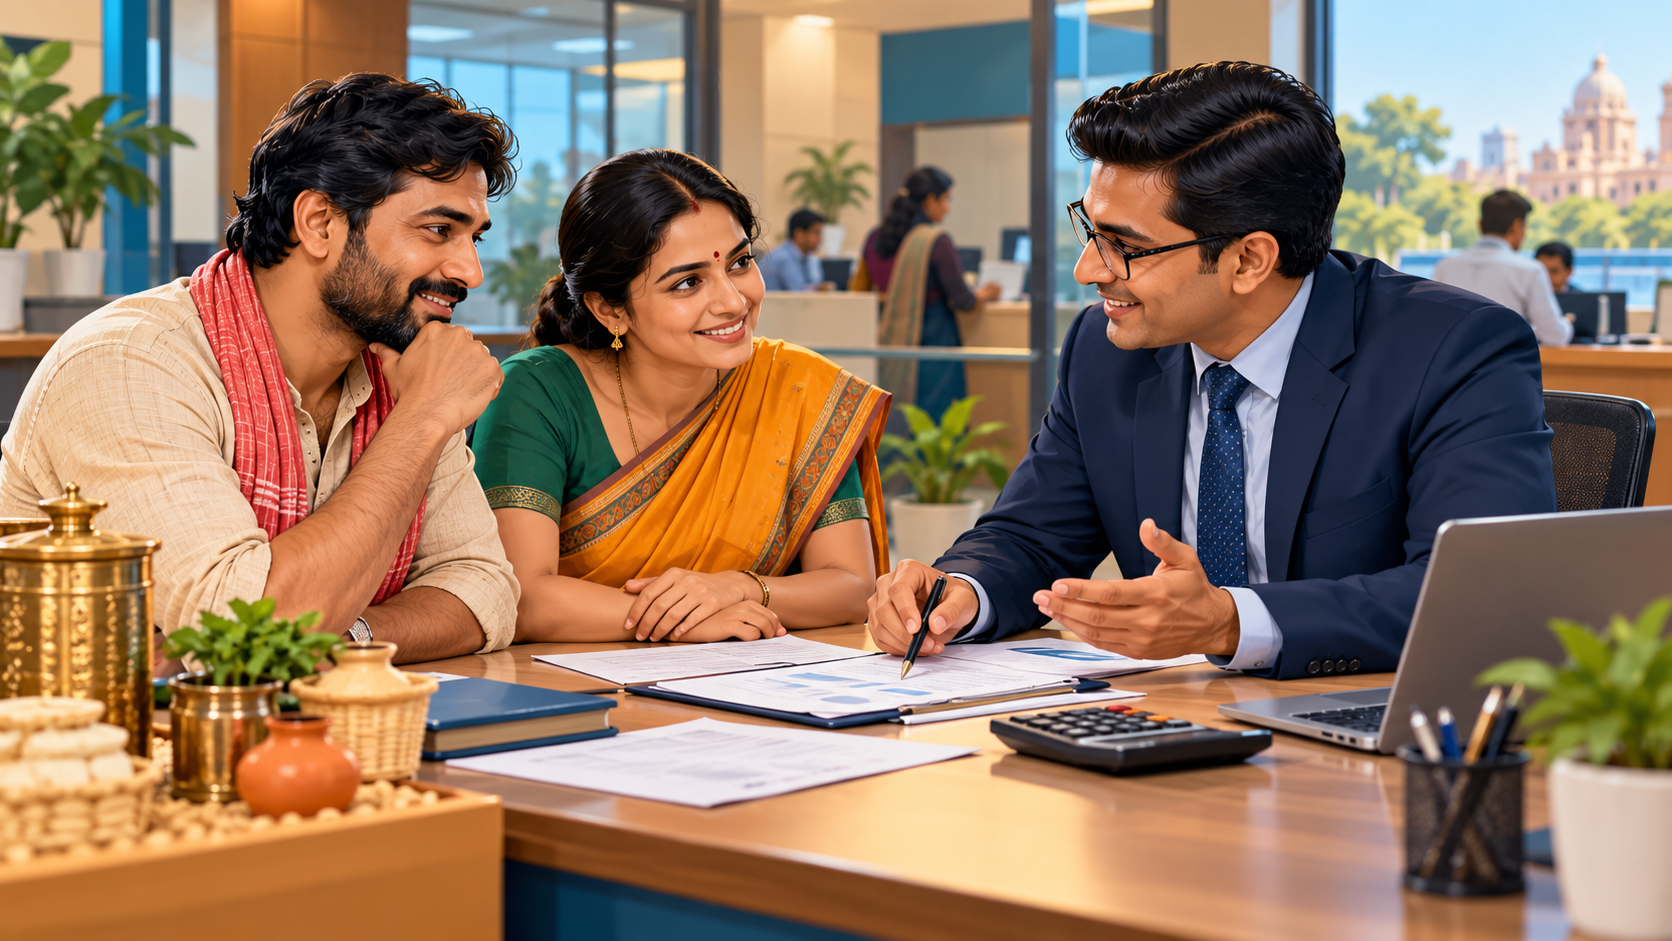
Featured image: representative AI-generated illustration.
share Share now

 All Services
 Classifieds Ads
 Service Experts
 Jobs
 Explore Travel
 News & Magazines
 Products
 Blogs
 Community




 Support